
Lesser know aspects of Transit & Storage Insurance Covers
Moving is stressful on its own. Packing up memories, dealing with timelines, and ensuring nothing gets lost, damaged or destroyed along the way are all real concerns. While you plan every detail of the move itself, don’t miss a critical part of protection: the right insurance for every phase of the journey.
If you are moving homes, relocating abroad, or placing items into storage, understanding the difference between transit insurance and storage insurance, and what it covers, is essential. It is important to know why bundled policies often fail and why separate insurance policies are key to keeping your belongings genuinely safe.
Customers often face unnecessary losses simply because they assume one insurance policy covers everything. Unfortunately, that’s rarely the case. This guide helps us understand the lesser-known aspects of moving insurance, common claim denials, and why you may need three separate covers (transit, storage, and redelivery insurance) depending on your moving situation.
Why Is Transit Insurance Alone Not Enough?
Transit insurance is typically designed to cover items only while they are being transported. It does not provide end-to-end protection. That means the moment the truck stops and your goods enter a warehouse, your protection may stop too. It applies only during the movement phase.
If your goods sit in a warehouse for more than 7 days, they are at risk unless separate storage insurance is active.
What Transit Insurance Should Cover
A good transit policy should ideally protect against:
- Damage caused by handling during loading and unloading (this depends on policy wording).
- Fire, accidents, and vehicle overturning incidents that may occur while the truck is on the road.
- Theft during transit, usually through forced entry or specific incidents.
- Natural disasters like floods or storms affecting goods in transit.
Where Transit Insurance Often Fails
These failures are rarely explained to customers upfront. Common situations include:
- No storage coverage: Once goods are unloaded into a warehouse, whether for a planned pause or unexpected delay and if it crosses 7 days of storage, then transit cover ends.
- Limited protection for last-mile delivery: When goods are taken out of long-term storage and transported again, the previous transit insurance often does not apply unless you buy a fresh policy for this last-mile delivery.
Bundled insurance, offered as a one-line add-on by some vendors, fails in real situations due to this reason.
What is the First Mile, Middle Mile, and Last Mile?
- First Mile: Refers to the phase of moving goods from your home to the storage facility or directly to a specific destination (such as your new home).
- Middle Mile: This is the period of time when your goods are stored in a warehouse.
- Last Mile: This refers to moving goods from the warehouse to your final destination.
Each phase has different risks. And unfortunately, no single insurance policy covers all three effectively. Thus, separate policies are essential to avoid losses later.
Why You Sometimes Need Three Separate Insurances
Depending on your situation, you may need:
- Transit Insurance: For movement from home to warehouse or directly to the destination.
- Storage Insurance: For goods kept in a warehouse (whether for 12 hours, 3 days, 3 months, or 3 years).
- Redelivery Transit Insurance: For moving goods out of storage to your new address.
Each policy covers a different phase of risk. When bundled together, insurers often add ambiguous conditions that allow them to deny claims later.
What is the Short Term Storage
A hidden risk no one talks about often is short term storage. This refers to the short, temporary stop your goods made at a warehouse, usually between 1 to 15 days, before continuing the journey. Many people assume this short wait is automatically covered in the transit insurance. It sometimes is not, and there is a fine print you should read carefully.
There are also soft storage limits that matter here.
- If your goods stay longer than 7 Days (even by a few hours), the insurer may consider them in storage, invalidating your transit claim.
- In peak moving seasons, delays are common. Drivers wait for approvals, trucks are re-routed, or containers get held for consolidation.
- If there’s any dispute about how long your goods were stationary, the claim can be rejected.
This is one of the most common causes of storage claim denial, especially for international moves.
Situations Where All Three Covers Are Absolutely Necessary
Below are examples of situations when you should always opt for separate transit and storage insurance.
- You don’t have the keys to your new home yet. If there’s a delay and your goods need to wait in a warehouse for any duration, get storage insurance.
- If you’re relocating internationally, the shipping involves multiple warehouses across cities and countries.
- There is a gap between move-out and move-in dates. If the gap is more than 7 days, it technically means your goods are “in storage.”
- If your goods are being consolidated (which is common in international moves), where containers are shared across clients.
- If your move involves multiple cities then your shipment may change trucks or stops at a transit warehouse. In this case you need layered coverage.
Transit Insurance vs Storage Insurance: The Real Difference
Here’s a simple comparison to understand why one cannot replace the other:
| Aspect | Transit Insurance | Storage Insurance |
| Coverage period | Only while goods are moving | While goods sit in a warehouse |
| Risks covered | Accidents, theft during transit, natural disasters en-route | Fire, burglary, theft, water leakage, rodents, pest damage, long-duration risks |
| When needed | First, middle and last mile when goods are on the truck | Period when goods are in a warehouse |
| Claim sensitivity | Highly time dependent | Occupancy and facility dependent |
Why a Professional Moving Partner Matters
Separate insurance policies can feel complicated, but a good, reputable moving company makes the process effortless. Globe Moving educates customers early, helps them assess risks, and ensure policies are compliant and clear. This prevents heartbreak, financial loss, and the stress of dealing with claim disputes later.
When you’re entrusting a lifetime of belongings to someone, you deserve more than convenience. You deserve protection that actually works.
Protect Your Belongings the Right Way
Your belongings carry stories, memories, emotional meaning and monetary value. Insurance is not just a formality; it’s the safety net that ensures those memories stay intact no matter how complicated your move becomes.
Take the time to understand the difference between transit and storage insurance, and whether redelivery coverage is required to avoid hassles and protect your goods at every stage, from the first mile to the last mile.
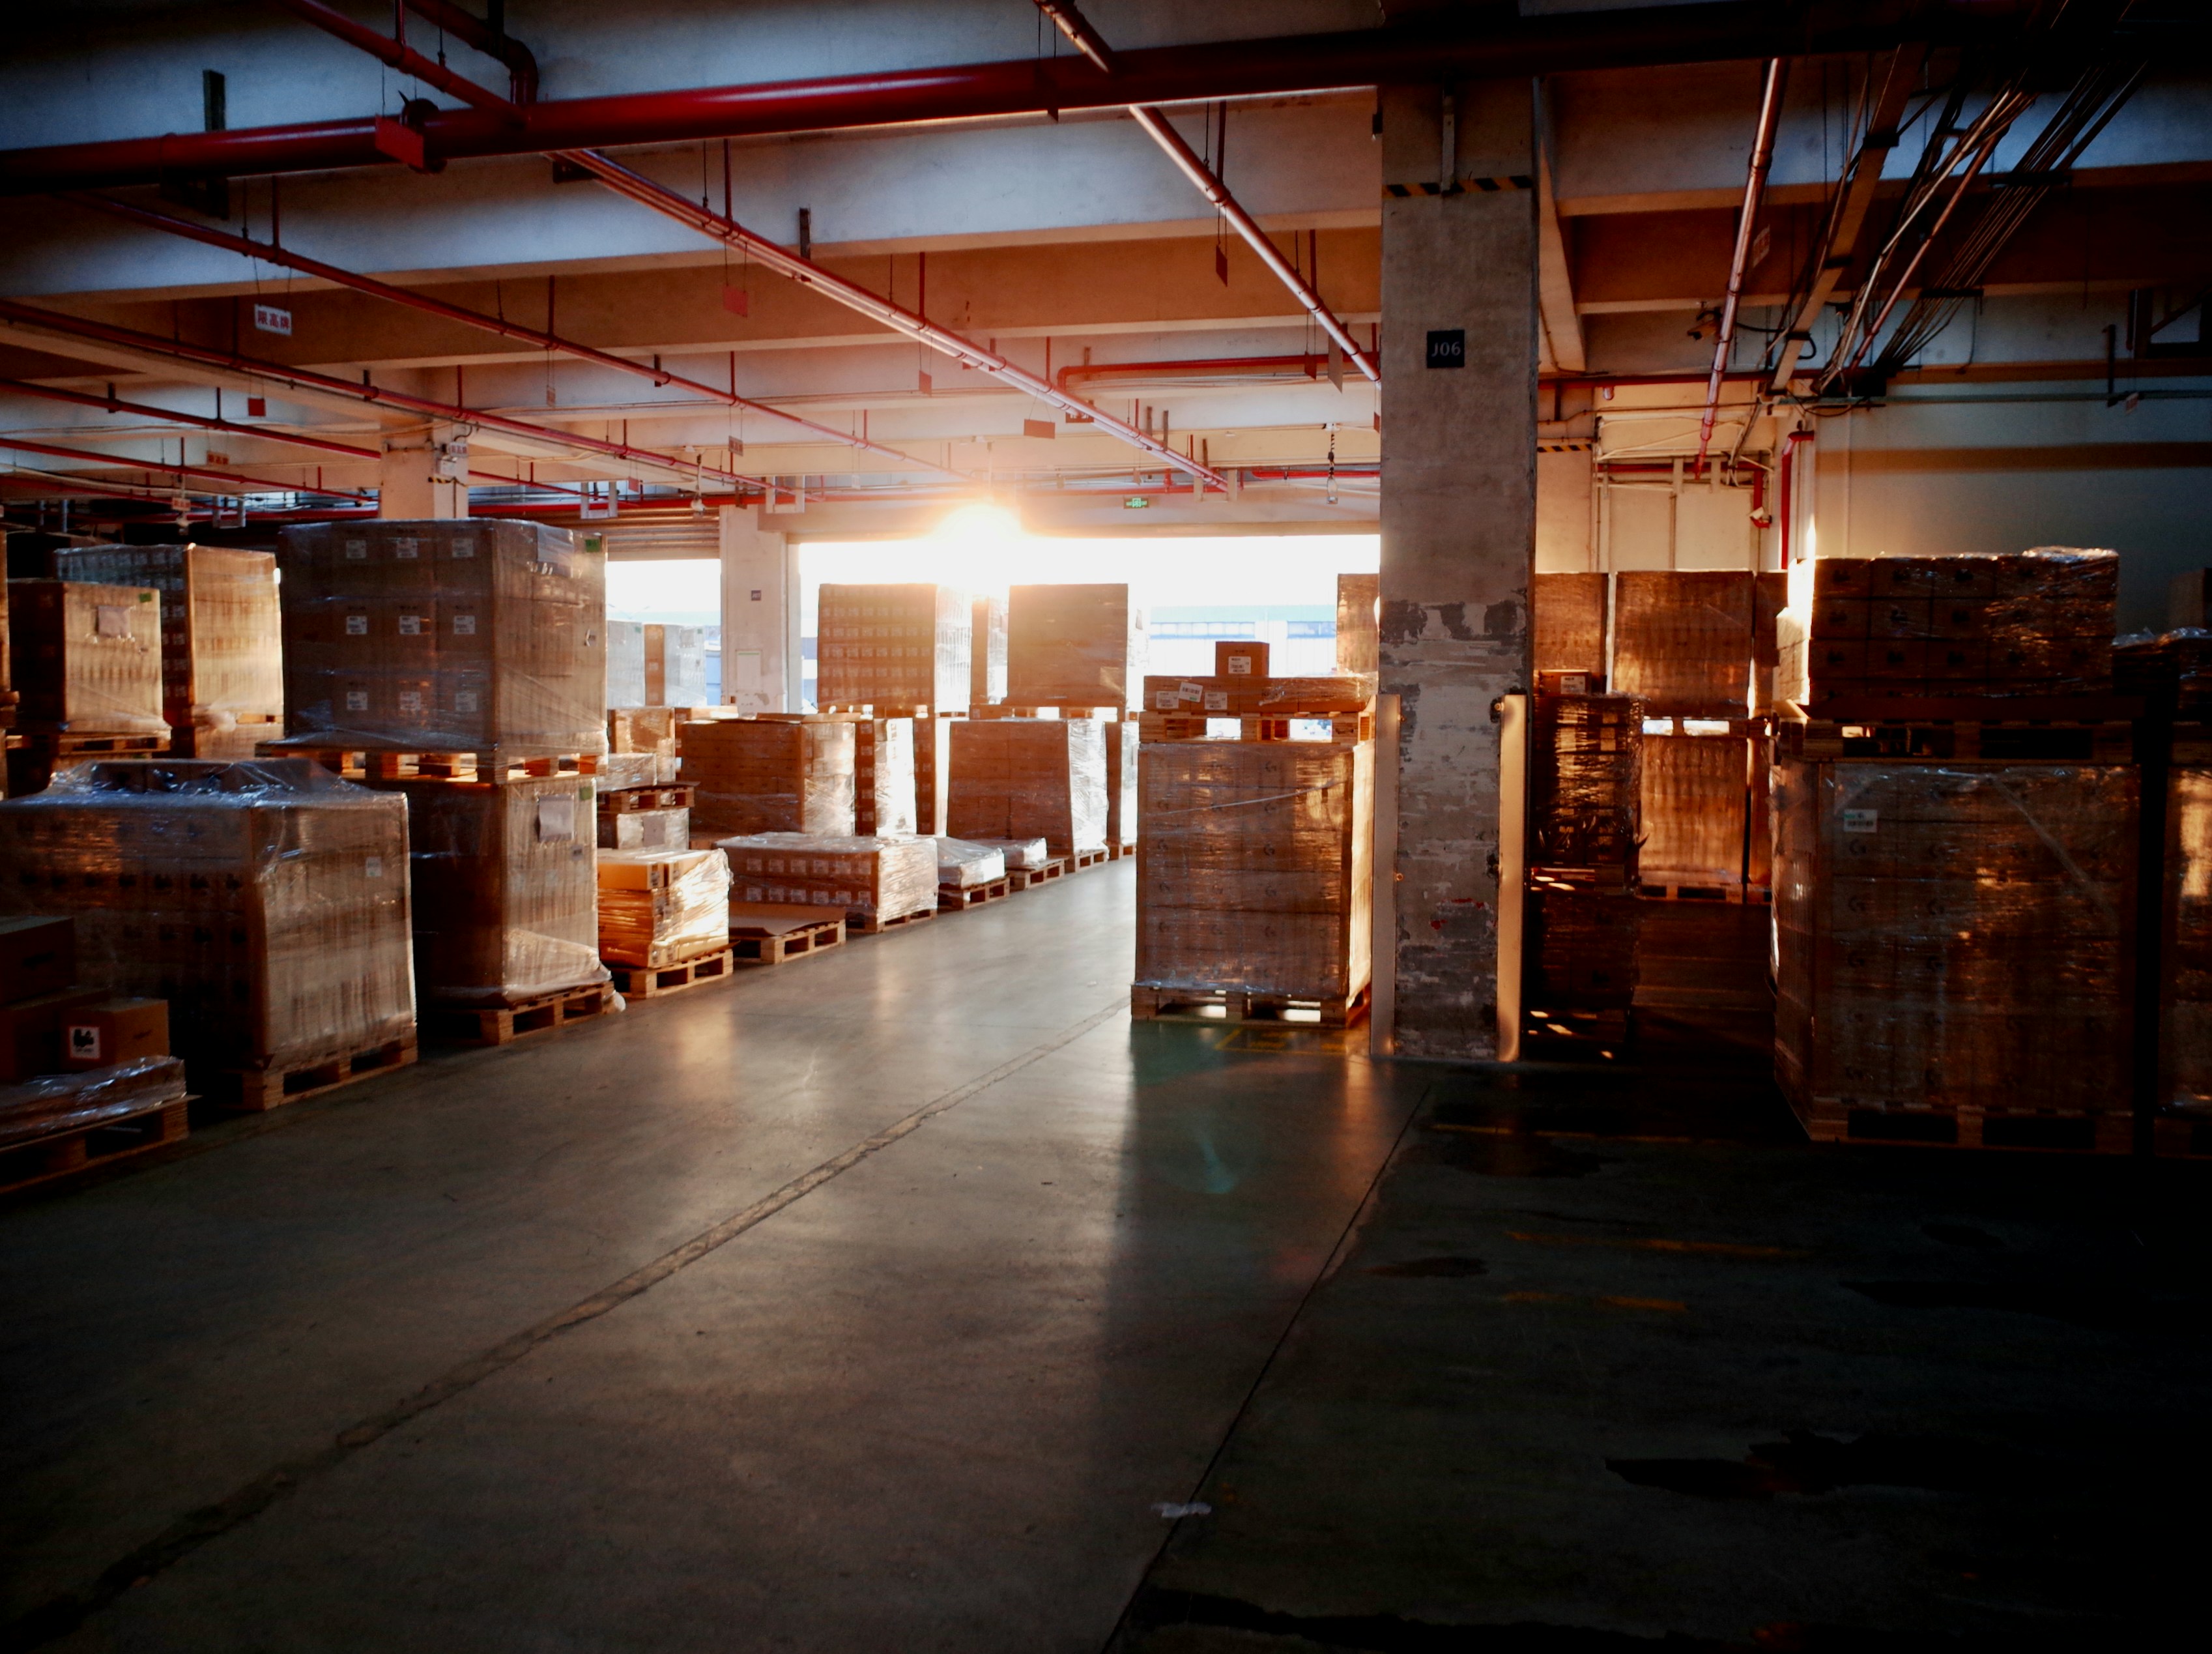
Photo by [Vida Huang] on [Unsplash]
Related links
Moving Insurance in India: Legal Rights and Responsibilities
Insurance for Short-Distance Moves: Why It’s Essential
Moving Insurance: Should You Handle It or Use Your Mover’s?