 FOR ENTERPRISESWorkforce MobilityRelocation support for employees and their families, managed end to end.FIDI-FAIM PLUS · 55+ YEARS · 180+ COUNTRIESFOR FAMILIES AND INDIVIDUALSLocal MovingSame-city home moves, surveyed and packed by one crew.FIDI-FAIM PLUS · 55+ YEARS · 180+ COUNTRIESFOR GLOBAL PARTNERSOrigin ServicesPacking, export documentation and dispatch from India.FIDI-FAIM PLUS · 55+ YEARS · 180+ COUNTRIESRESOURCESBlogs & GuidesPractical advice for planning a move.FIDI-FAIM PLUS · 55+ YEARS · 180+ COUNTRIESABOUT GLOBE MOVINGAbout Globe MovingWho we are and how we work.FIDI-FAIM PLUS · 55+ YEARS · 180+ COUNTRIES
 GUIDES AND TOOLSEverything you need to plan a move.WHO WE AREOne partner. Every move.
The NRI Return: Understanding the Financials of Moving Back to India
Executive Summary
Financial considerations for NRIs moving back to India refer to the economic planning required when relocating from another country to resume residence in India. This includes matters such as taxation, banking arrangements, asset management, and currency implications that can affect financial stability after relocation. The information is most relevant for Non-Resident Indians, returning professionals, and financial decision-makers planning repatriation.
Why Returning NRIs Often Face Complex Financial Transitions When Relocating to India
For many Non-Resident Indians (NRIs), the idea of moving back home carries a mix of excitement and apprehension. Beyond the emotional pull of family and familiarity, the decision often hinges on one crucial question: “Can I maintain a comfortable lifestyle in India?”
Understanding the financial landscape, from cost of living and salary expectations to taxation and investments, is essential before you pack your bags. Let’s take a detailed look at the financial realities of returning to India in 2025, and how to prepare for a smooth transition.
Cost of Living Deep Dive: What Does “Comfortable” Really Mean in India?
India’s cost of living varies dramatically between Tier 1 and Tier 2 cities. What’s considered “comfortable” in Mumbai or Bangalore may feel luxurious in Pune or Coimbatore.
Here’s a breakdown of typical monthly expenses for a family of four (as of 2025):
| Expense Category | Tier 1 Cities | Tier 2 Cities |
| Housing (3BHK Apartment, Good Area) | ₹70,000 – ₹1,40,000 | ₹30,000 – ₹70,000 |
| Utilities (Electricity, Internet, Gas, Water) | ₹10,000 – ₹15,000 | ₹6,000 – ₹10,000 |
| Groceries & Essentials | ₹20,000 – ₹35,000 | ₹6,000 – ₹10,000 |
| Domestic Help | ₹8,000 – ₹15,000 | ₹4,000 – ₹8,000 |
| Transportation (Fuel, Maintenance, Public Transport) | ₹5,000 – ₹10,000 | ₹2,000 – ₹7,000 |
| Education (Private Schools) | ₹1,50,000 – ₹2,50,000 per year | ₹70,000 – ₹1,20,000 per year |
| Healthcare & Insurance | ₹5,000 – ₹15,000 | ₹5,000 – ₹10,000 |
While costs are rising in major metros, Tier 2 cities are becoming attractive for returning NRIs due to lower living expenses, better air quality, and improving infrastructure.
Salary Analysis: What Is a “Good Salary” in India Today?
When moving back, one of the biggest mindset shifts for NRIs is aligning expectations with Indian salary structures.
- Understanding Local Pay Scales
- In Tier 1 cities, a mid-to-senior professional in sectors like IT, consulting, or finance earns between ₹30–70 lakh annually, depending on role, experience, and sector; verify with market data such as Glassdoor or Payscale as well.
- In Tier 2 cities, packages are typically 20–30% lower, but living costs are also significantly reduced.
If you’ve been earning abroad in USD, GBP, or AED, this can feel like a steep cut. However, when adjusted for local cost of living and purchasing power parity, salaries in India can still sustain a high standard of living.
- What Is the Income to Live Comfortably in India?
A single professional can live comfortably on:
- ₹1.5–2 lakh per month in Tier 1 cities, indicative monthly take-home required for good lifestyle.
- ₹80,000–1.2 lakh per month in Tier 2 cities.
For families with children, add another ₹1–1.5 lakh per month for education, domestic help, and healthcare.
3. The “Top 1% Salary” Benchmark
The estimates for the income needed to be in India’s top 1% vary by data source and methodology; published ranges often put individual top-1% income somewhere in the low-tens of lakhs up to ~₹40–55 lakh per year. Use these numbers only as a broad benchmark, not a precise threshold.
Tax Implications: The Crucial Shift from NRI to Resident
Taxation is often an overlooked aspect of returning to India, yet it can have significant financial implications if not planned properly.
- Understanding NRI vs. Resident Status: Your tax status depends on the number of days you spend in India:
- NRI (Non-Resident Indian): If you stay in India for less than 182 days in a financial year, you are considered an NRI for tax purposes. As an NRI, you are only taxed on income earned or received within India. Your foreign income, earned outside work of India, is not taxed in India.
- Resident (RNOR or Ordinary Resident): If you stay in India for 182 days or more, or meet certain conditions over the past several years, you are classified as a Resident. In this case, your global income becomes taxable in India.
What Happens in the Year You Move Back?
The year you return to India, you may qualify as a Resident but Not Ordinarily Resident (RNOR). This status means that your foreign income is not taxable in India during that period. However, once you become a Resident and Ordinarily Resident (ROR), your global income—including income from outside India—becomes subject to Indian tax laws.
- Double Taxation Avoidance Agreements (DTAA): India has DTAA treaties with over 90 countries. These agreements ensure you don’t pay taxes twice on the same income. For example:
- If you earned dividends or salary abroad and have already paid tax there, you can claim credit or exemption while filing in India.
- It’s crucial to maintain documentation (Form 67, tax certificates) to support your claims.
- Filing Returns: Even if your income is below the taxable limit, filing returns helps:
- Avoid future complications during foreign remittance or property sale.
- Maintain clear records for any overseas income declared under DTAA.
If you have assets or bank accounts abroad, you’ll need to disclose them once you become a resident. Consulting a tax advisor familiar with NRI returns can help you avoid compliance issues.
Financial Planning: Managing Your Global Assets
Moving back doesn’t mean you must cut ties with your financial life abroad. With thoughtful planning, you can retain investments overseas while building a strong base in India.
- Repatriating Funds
Decide whether to:
- Repatriate money to India using NRE/NRO accounts, or
- Keep funds abroad for future international commitments (like education or travel).
NRIs returning permanently should convert their NRE accounts to resident accounts and NRO accounts to regular savings accounts once their tax status changes.
- Investing in India
Consider diversifying into:
- Mutual funds and SIPs which are ideal for long-term wealth creation.
- Fixed deposits, currently offering 5-7% interest rates annually.
- Real estate is still a preferred asset class for many NRIs, especially in Tier 2 cities with growth potential.
- Health and life insurance is essential for financial security in India’s private healthcare ecosystem.
- Handling Foreign Investments
If you have 401(k)s, ISAs, or offshore property, consult a cross-border financial planner before taking any action. Certain assets can trigger tax events when liquidated or transferred. Strategic timing can help minimize tax exposure.
- Building a Local Safety Net
Ensure you set up:
- A local emergency fund covering 6-12 months of expenses.
- Medical coverage for the family, as employer-provided health plans may be limited.
- A retirement plan based on Indian cost of living, inflation, and lifestyle expectations.
Beyond Finances: Planning Your Physical Move
While finances dominate most return plans, logistics can be equally challenging, especially if you’ve been abroad for years. Managing household goods, vehicles, and personal effects requires careful coordination.
This is where Globe Moving, a trusted relocation partner, can help. Globe Moving specializes in end-to-end international relocation services from secure shipping to settling-in support in your destination city. Having a professional handle logistics ensures your return is smooth, secure, and stress-free.
Balancing Emotion and Economics
Returning to India is as much a financial decision as it is an emotional one. Understanding your expenses, tax responsibilities, and investment opportunities can help you make the move with confidence. Here’s a quick recap:
- Tier 1 cities offer top amenities but come with higher costs. Tier 2 cities provide a better balance between comfort and affordability.
- Be proactive about tax residency and DTAA compliance to avoid penalties.
- Maintain a global financial strategy that protects your assets while leveraging opportunities in India.
With clear planning, and the right relocation support, your return can mark a homecoming and the start of a secure, rewarding new chapter in India.
Note on figures: the salary, rent, and interest-rate ranges in this guide are indicative and depend on city, role, and market conditions. Tax and compliance rules also change over time — the guide cites core rules (e.g., Indian residency tests and GST e-way thresholds), but please consult a qualified tax advisor or the issuing authority for decisions affecting your situation. (Sources: Indian Income Tax Department; GST guidance; leading bank rate pages.)
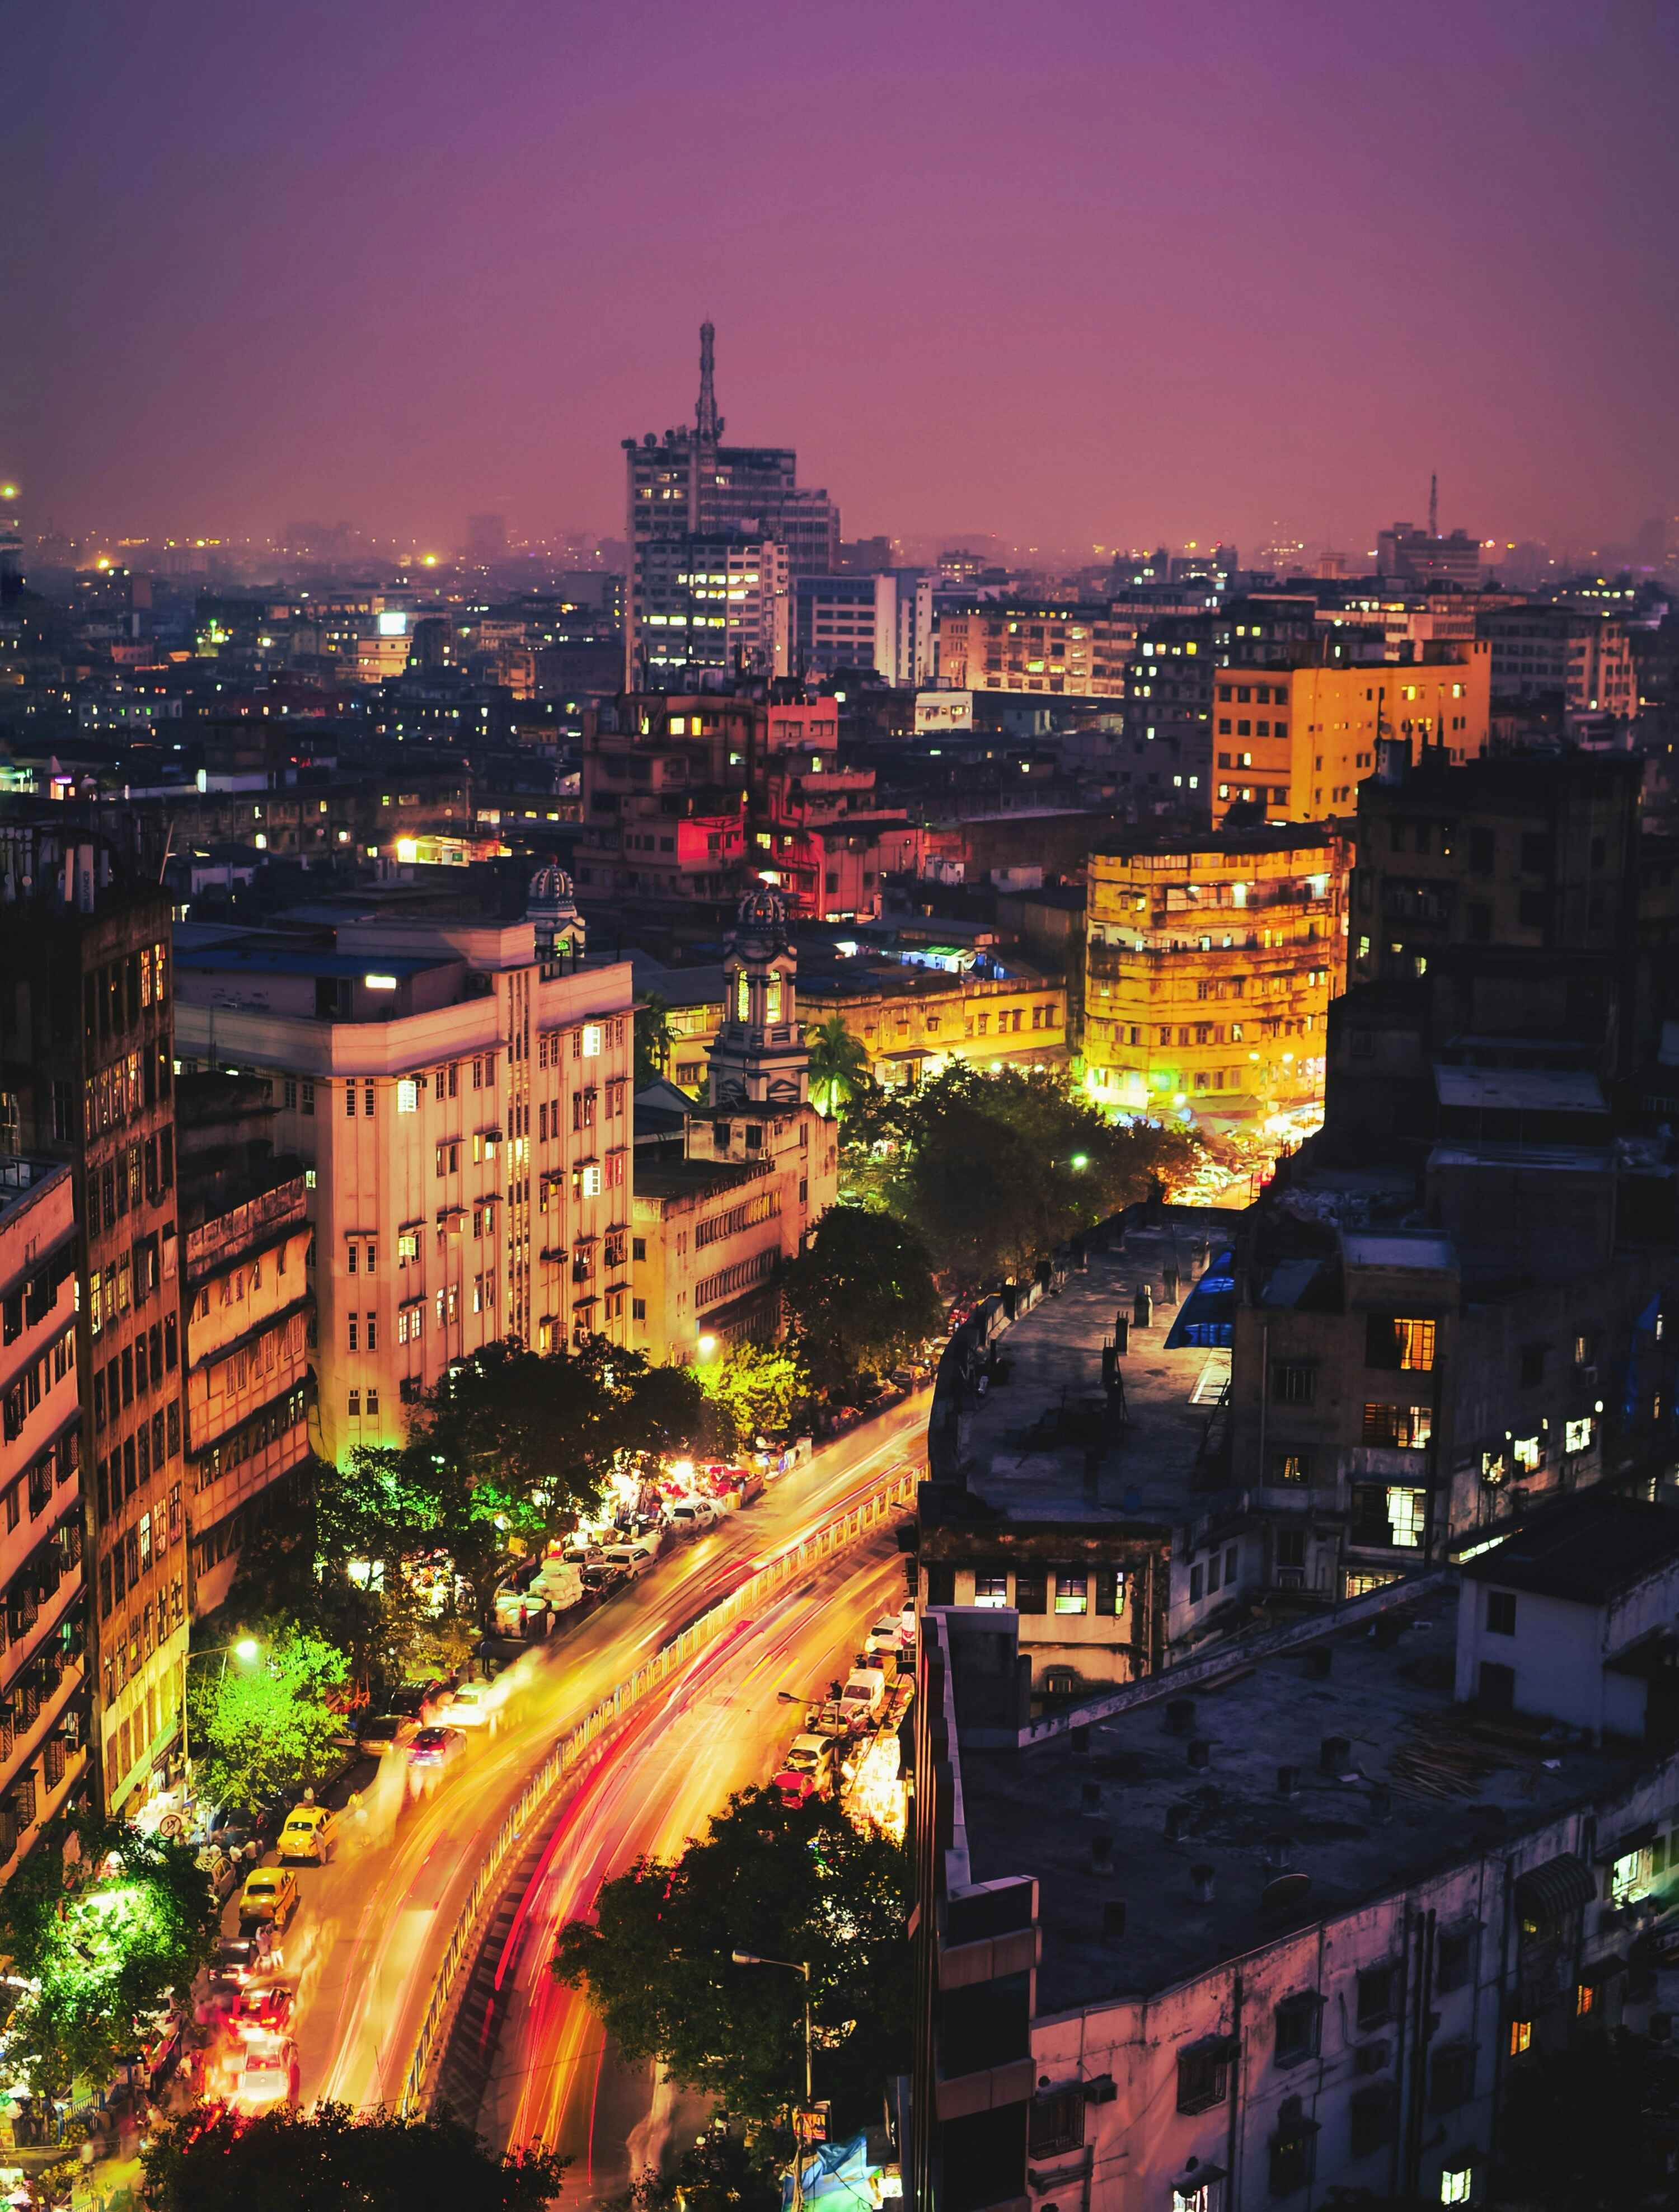
Photo Credits by Arindam Saha on Unsplash
Make in India — Opportunities for All
Challenges faced by expats when moving to India
Moving to India – How to Make It a Memorable Experience